How to Not Qualify for a Mortgage

Dan Caird • May 5, 2021

If you have no desire at all to qualify for a mortgage, here are some great ways to make sure you don’t accidentally end up buying a house and taking out a mortgage to do so.


One of the best ways to ensure you won’t qualify for a mortgage is to be unemployed. Yep, banks hate lending money to unemployed people! Okay, so you have a job. Well, that’s okay, you can always unexpectedly quit your job just as you are trying to arrange financing! Even if you are making a lateral move, or taking a better job than the one you have now, that’s cool… any change in employment status while you are looking to get a mortgage will most likely wreck your chances of getting a mortgage for a while. This is because lenders want to see stability; they want to know that you have been in your current position for some time, that you are past probation, and that everything is working out well. By changing jobs right when you are looking to buy a property, you won’t install the lender with confidence, and they probably won’t give you a mortgage. Mission accomplished.
Don’t wanna buy a house? Well, then it’s best you don’t save any money. Better yet, you should probably borrow as much money on credit as you can. One of the main qualification points on a mortgage is called your debt-service ratio. Simply put, the more money you owe in consumer debt, the less money you will qualify to borrow on a mortgage, because your ratio of income compared to your debt is higher when you owe more money. Consider this permission to go and finance a Harley-Davidson. Do it, right now. Not a big fan of motorcycles? That’s cool; a Ford 150 should do the trick nicely. The key here is to make sure you add as much monthly payment as you can. The bigger the payment, the better.
But let’s say that unfortunately your debt-service ratios are in line, you have been able to save up the necessary 5% down payment, and you are on your way to buying a house. What do you do? Ugly documentation! A great way to make sure your lender feels uncomfortable is to have really terrible bank statements. Typically when proving your down payment, the lender will require 90 days’ history of your account(s), with your name on the statement, showing that you have accumulated the down payment over time. Want to really mess things up? Make sure there are lots of deposits over $1000 that can’t be substantiated. This will look like money laundering. If that doesn’t work, you can always black out your “personal information.” Just use a black Sharpie and make your bank statements look like a classified FBI document. Lenders hate that!


So you’ve got a great job and lots of money… don’t panic, you can still absolutely wreck your chances of qualifying for a mortgage. Just don’t pay any of your bills on time. Seriously, borrow lots of money, and then stop paying! Boom. Why would any lender want to lend you money when you have a great track record of not paying back any of the money you borrow? Now, if this feels morally wrong, okay, here is an ethical way to wreck your credit. Don’t pay that cell phone bill out of principle. We’ve all been there — roaming charges, extra data charges that the cell company added on your bill… choose not to pay this on principle. This is a great way to sink your chances of getting a mortgage, I mean, how are you supposed to know that some collections (like cell phones) will show up on your credit report?


Last, if you want to make sure you never get financing, insist on buying the worst house in a bad neighbourhood. You see, the property you are looking to buy is very important to the lender. If they lend you the money to buy it and you stop making the payments, they will be forced to repossess and sell it. They are going to make sure they can recoup their initial investment. So, a “handyman special, fixer upper, with lots of potential” is a great option. As everyone knows, those words are code for “a giant dump.” Bonus points if you get those terms written in the MLS listing. Yep, insist on buying something that is falling apart and stick to it; don’t ever consider buying a solid home in a good neighbourhood.
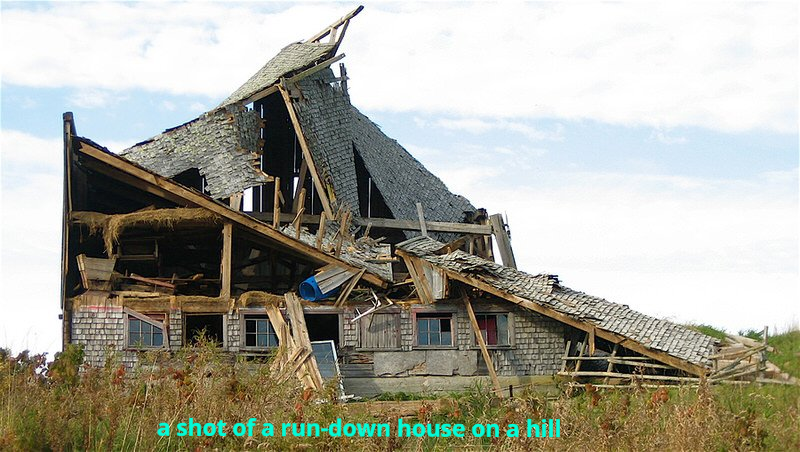
So there you have it, if you don’t want a mortgage, no problem. Quit your job, borrow lots of money, wreck your credit, and insist on buying a dump.


However, on the off chance you feel homeownership is right for you, contact me anytime, I can help you put a plan in place to avoid these (and many more) mortgage qualification pitfalls.

Share
DAN CAIRD
Mortgage Agent | DLC

RECENT POSTS
By Dan Caird • October 14, 2026
Can’t Find the Right Home After You’re Pre-Approved? There’s Another Option The best place to start any home purchase is with a mortgage pre-approval. It gives you clarity around your budget and lets you shop with confidence. But what happens when you’ve been pre-approved, you know where you want to live—and nothing suitable fits your price range? This is a common challenge, especially for first-time homebuyers. Before buyer fatigue sets in, it may be worth considering a different approach: buying a home that needs work and financing the renovations as part of your mortgage . What Is a Purchase Plus Improvements Mortgage? A purchase plus improvements program allows you to buy a property and include the cost of approved renovations directly in your mortgage. This can be a great solution if: You can’t find a move-in-ready home within budget You’re open to renovations You want to customize the home from the start It opens up more options and can help you get into a location or property that would otherwise be out of reach. How the Process Works While the idea is straightforward, the process itself is structured and requires planning. Here’s a high-level overview: Renovation quotes are required upfront You’ll need detailed quotes for the work you want completed before final mortgage approval. Renovations must add value The lender must be satisfied that the improvements will increase the property’s value accordingly. Funds are reimbursed, not advanced You pay for the renovations initially. Once the work is completed and verified by an appraiser, the lender reimburses you and adds the cost to your mortgage. With the right guidance, this process is very manageable—but it’s important to understand the steps before committing. Is This Program Right for You? Purchase plus improvements isn’t for everyone. Buying a home is already a big undertaking, and adding renovations can increase stress—especially if timelines, budgets, or contractors become challenging. That said, if you’re financially prepared and like the idea of shaping the home to fit your needs, this program can be an excellent way to get more value and flexibility from your purchase. Final Thoughts If you’re struggling to find the right home after being pre-approved, you may not need to lower your expectations—you may just need a different strategy. If you’d like to explore whether a purchase plus improvements mortgage makes sense for you, feel free to connect. I’d be happy to walk you through the process and outline exactly what this option would look like in your situation.
By Dan Caird • October 7, 2026
Missed a Credit Card or Line of Credit Payment? Here’s What to Do If you’ve missed a payment on a credit card or line of credit and you’re worried about how it might affect your credit—or your future mortgage—this is for you. First things first: 👉 If you currently have an overdue balance, log in and make the minimum payment now. Seriously. Do that first. Everything else can wait. If You’re Only a Few Days Late Here’s the good news: Credit bureaus don’t record late payments until they reach 30 days past due. So if you missed a due date by a few days and paid it as soon as you noticed, it typically won’t show up on your credit report as a late payment—as long as you’re under the 30-day mark. That said, it never hurts to double-check. You can call your credit card company, explain what happened, and confirm the account is back in good standing. If you normally pay on time, they may even reverse the interest charged. It doesn’t hurt to ask. If You’re 30, 60, or 90 Days Behind If payments have gone past 30 days, your credit has likely been impacted—but the situation is still fixable. The most important step is to: Bring all accounts current as soon as possible Make at least the minimum payment on every account The faster you catch up, the more you limit the damage. Ignoring missed payments only makes things worse. If Cash Flow Is Tight If you’re struggling to make payments, communication matters. Contact your lender and keep them informed—even if you can’t pay right away. Lenders are far more willing to work with you when you’re transparent. What hurts your credit most is silence . If lenders don’t hear from you after repeated missed payments, they may write the balance off as bad debt and send it to collections. Collections can significantly impact your credit and stay on your report for years. How This Affects Mortgage Qualification Repeated missed payments can make qualifying for a mortgage more difficult—but timing matters. Once you’re back to making regular, on-time payments: Your credit can improve over time The impact of past mistakes becomes less significant If you’re planning to buy a home in the next couple of years, addressing credit issues early gives you far more options later. Final Thoughts Missing a payment doesn’t mean you’re “bad with money,” and it doesn’t mean homeownership is off the table. What matters most is how quickly you respond and how consistent you are going forward . If you’d like help reviewing your credit report or understanding where you stand from a mortgage perspective, feel free to connect. I’d be happy to walk through it with you and help you create a clear path forward.